 By admin
The Quiet Power of Reinvesting What You Earn
Most investors spend their energy thinking about which stocks to buy. Far fewer spend it thinking about what to do with the income those stocks produce. That's a missed opportunity, because the way you handle dividends can matter as much as the stocks you choose. Dividend reinvestment is one of the simplest and most powerful ideas in all of investing: instead of taking your dividend checks as cash, you use them to buy more shares of the company that paid them. It sounds almost too basic to matter, but over decades it can transform a modest portfolio into something far larger than most people expect. The magic isn't in any single dividend payment. It's in what happens when those payments start earning returns of their own.
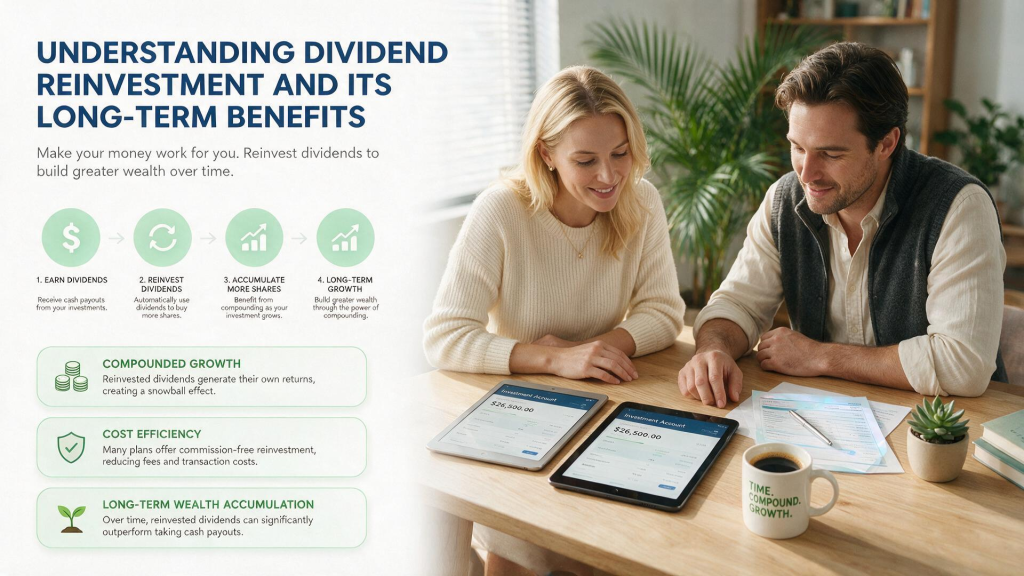
Here's the intuition. When a company pays you a dividend, you have a choice. You can spend it, you can leave it in cash, or you can put it back to work. Reinvesting puts it back to work immediately, buying more shares that will themselves generate dividends next quarter and the quarter after that. Each round of dividends buys more shares, which produce more dividends, which buy more shares. This is the compounding process in its purest form, and it's why patient investors who reinvest consistently often end up with dramatically more than those who take the cash. The difference compounds quietly for years, then becomes impossible to ignore.
What makes this especially valuable is that it happens automatically for many investors, which removes the temptation to spend the cash or time the market. You don't have to decide whether today is a good day to buy — the reinvestment happens on a schedule regardless of what the market is doing. Over time, that means you're buying more shares when prices are low and fewer when prices are high, a natural form of dollar-cost averaging that smooths your entry points. The discipline of automatic reinvestment does more for most portfolios than any clever timing decision ever could, and it does it without requiring you to predict anything.
How Dividend Reinvestment Plans Work
A DRIP investment strategy — short for dividend reinvestment plan — is the mechanism that makes this easy. Many companies offer DRIPs directly to shareholders, allowing them to reinvest dividends automatically and often at little or no cost. Brokerages also offer similar programs, and most of them let you enroll in automatic reinvestment for any dividend-paying stock or fund you own. Once you're enrolled, the process runs in the background: the dividend is paid, the shares are purchased, and your position grows without any action on your part. You can usually turn it off if you need the cash, but leaving it on is the default that builds wealth.
DRIPs come in two main flavors. Company-sponsored plans let you buy shares directly from the company, sometimes with no commission and sometimes with a small discount to the market price. These plans are popular with long-term investors who want a simple, low-cost way to build a position steadily over time. Brokerage-sponsored plans are more flexible because they let you reinvest dividends across a wide range of holdings in a single account, and they often include fractional shares so that every dollar gets put to work. The right choice depends on your situation, but the common thread is automation. The less you have to think about it, the more likely it is to keep happening through good markets and bad.
There are a few practical details worth understanding. Reinvested dividends are still taxable in most cases, even though you never see the cash. The IRS treats them as income, which means you'll owe taxes on them in the year they're paid unless they're held in a tax-advantaged account like an IRA or 401(k). That's not a reason to avoid reinvesting — it's a reason to keep good records and to hold dividend-paying stocks in tax-sheltered accounts when you can. It's also worth checking whether your plan charges fees, since even small fees can add up over decades. Most brokerage reinvestment programs are free, but it's worth confirming before you enroll.
Another detail is that reinvestment changes your cost basis, which matters when you eventually sell. Each reinvested dividend creates a new tax lot with its own purchase price, and tracking those lots is important for calculating capital gains accurately. Most brokers handle this automatically now, but it's worth verifying that your records are complete. The administrative side of reinvesting isn't glamorous, but getting it right keeps you from losing money to taxes or paperwork errors later. Set it up correctly once, and the system mostly takes care of itself from there.
Dividend Growth and the Compounding Engine
Reinvestment becomes even more powerful when it's paired with dividend growth investing, the strategy of owning companies that raise their dividends consistently over time. A company that pays a 3% dividend today and raises it by 6% or 7% a year will eventually be paying far more than 3% on your original investment, and every one of those increases gets reinvested into more shares. This creates a double compounding effect: the dividend itself grows, and the number of shares you own grows at the same time. The combination is what turns a modest starting position into a serious income stream over a couple of decades.
Companies that can raise their dividends year after year tend to be high-quality businesses. They generate consistent free cash flow, they have manageable debt, and they operate in industries that aren't wildly cyclical. A long track record of dividend increases is one of the clearest signals that management is confident in the business and committed to sharing its success with shareholders. That doesn't guarantee future performance, but it's a meaningful sign of durability. Investors who focus on these companies often find that the dividend growth itself does much of the work, quietly raising their income and their share count without requiring any dramatic decisions.
The compounding math is worth sitting with for a moment. Suppose you own a stock yielding 3% and the company raises its dividend 7% a year. After ten years, the dividend on your original investment is roughly double what it was. After twenty years, it's nearly quadruple. If you've been reinvesting the whole time, your share count has grown substantially as well, so the actual income you're receiving is far higher than the original yield suggests. This is how compound investment returns work in practice — slowly at first, then with increasing momentum. The early years feel unremarkable, which is why so many people give up before the curve bends upward.
The flip side is that this process takes time, and it rewards investors who start early and stay consistent. Someone who begins reinvesting in their thirties will see far more benefit than someone who starts in their fifties, simply because there are more years for the compounding to work. That's not a reason to avoid starting later — it's a reason to start as soon as you can and to keep going. The investors who build meaningful dividend income streams aren't usually the ones who picked the single best stock. They're the ones who picked reasonably good companies, reinvested consistently, and let time do the heavy lifting.
Building Passive Income Through Stocks
One of the most attractive aspects of dividend investing is the potential for passive income from stocks. Once a portfolio is established, it can generate regular cash payments without requiring you to sell assets or actively manage anything. For retirees, that income can supplement Social Security and pensions. For younger investors, it can provide flexibility — the option to work less, pursue other interests, or simply have a cushion. The appeal of passive income is real, but it's important to understand that building it takes time and consistency. Nobody builds a meaningful income stream overnight.
The key is to think of dividends as a long-term project rather than a quick payoff. A portfolio yielding 3% on $100,000 generates $3,000 a year, which isn't life-changing. But if you reinvest those dividends and the underlying companies raise their payouts over time, the income grows steadily. After a decade or two, that same portfolio might be generating $10,000 or $15,000 a year, and the growth continues from there. The early years feel slow, but the later years more than make up for it. The investors who succeed are the ones who stay patient during the slow phase and don't abandon the strategy because the checks seem small at first.
It's also important to be realistic about what dividends represent. They aren't free money — they come out of the company's earnings, and a high yield can sometimes be a warning sign that the payout is unsustainable. A company paying 8% when its peers pay 3% might be on the verge of cutting its dividend, which would hurt both your income and your share price. The safer approach is to focus on companies with reasonable payout ratios, growing earnings, and a long history of maintaining or increasing their dividends through tough times. Sustainability matters more than yield, because a cut dividend erases years of compounding in an instant.
Diversification across sectors and companies also matters for income investors. Relying on a handful of dividend stocks leaves you vulnerable to a single company cutting its payout, which can be a serious blow if you depend on the income. Spreading your holdings across utilities, consumer staples, healthcare, financials, and other sectors reduces that risk and smooths your income over time. It also gives you exposure to different growth drivers, which can help your dividends keep rising even if one industry hits a rough patch. The goal is a portfolio that can keep paying you through a variety of conditions, not one that maximizes yield at the expense of durability.
Putting Reinvestment to Work in Your Portfolio
The practical steps for putting dividend reinvestment to work are straightforward. First, decide which accounts should use it. Tax-advantaged accounts like IRAs and 401(k)s are ideal because reinvested dividends aren't taxed as they're paid, which lets the full amount compound. In taxable accounts, reinvestment is still worthwhile, but you'll want to keep good records and be mindful of the tax drag. Many investors hold their highest-yielding stocks in tax-sheltered accounts and their lower-yield growth stocks in taxable ones, which is a reasonable way to manage the tax impact of dividends.
Second, enroll in automatic reinvestment for every eligible holding. This is usually a matter of checking a box at your brokerage or signing up for a company's DRIP directly. Once it's on, leave it on. The whole point is to remove the decision from your hands, so that reinvestment happens consistently whether the market is up, down, or sideways. If you're tempted to turn it off during a downturn, remind yourself that lower prices mean your dividends buy more shares, which is exactly what you want when you're in the accumulation phase. Turning off reinvestment during a crash is one of the most common and costly mistakes income investors make.
Third, review your holdings periodically to make sure the dividend strategy is still working. Companies can change, and a dividend that looked safe five years ago might be at risk today. Check payout ratios, earnings growth, and debt levels, and be willing to replace a holding if the fundamentals have deteriorated. Reinvestment is powerful, but it works best when it's paired with quality holdings that can sustain and grow their payouts over time. A portfolio of weak dividend payers will underperform no matter how diligently you reinvest, so the underlying selection still matters.
Finally, be patient and let the process work. Dividend reinvestment is one of those strategies where the early results are underwhelming and the later results are impressive. The investors who benefit most are the ones who start early, stay consistent, and resist the urge to tinker. It's not exciting, and it won't make headlines, but it's one of the most reliable ways to build wealth in the stock market. Set it up, leave it alone, and give it time — the compounding will do the rest.