 By admin
The Calculator That Makes Time Visible
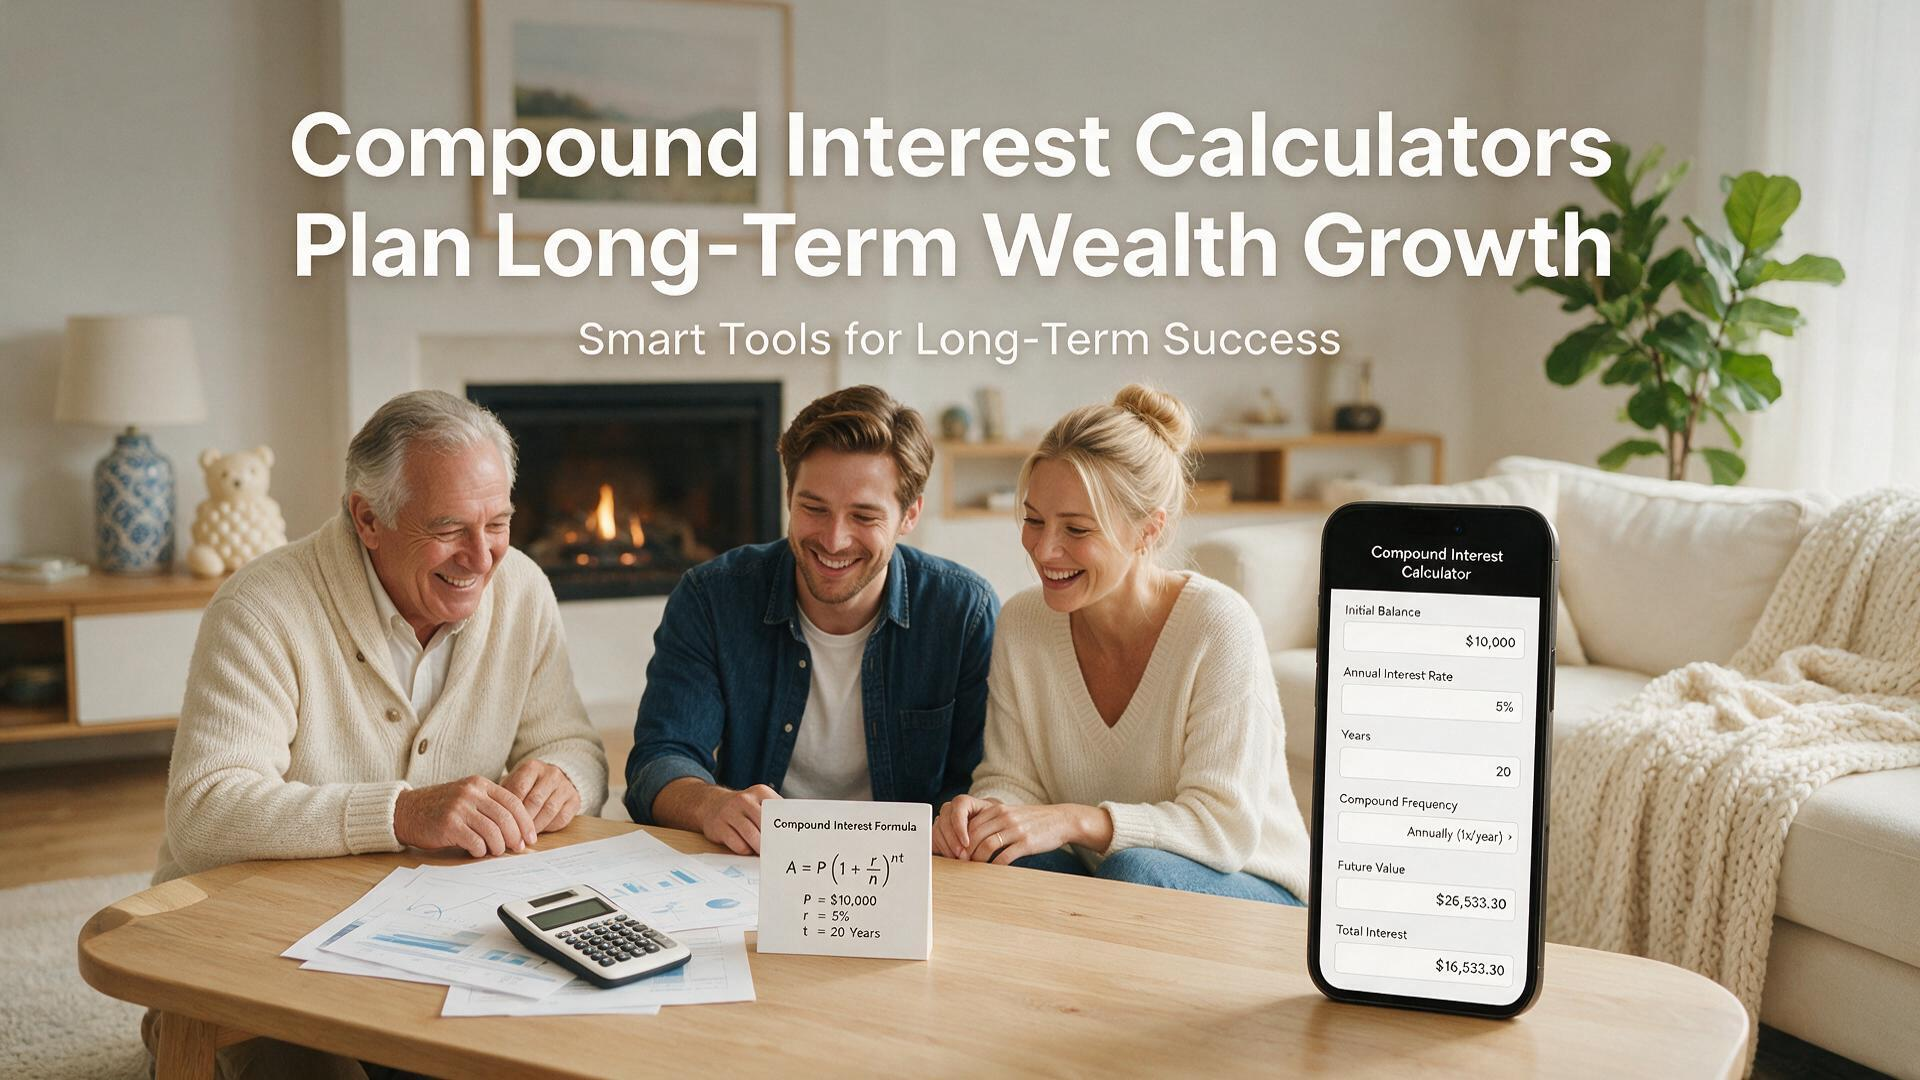
Most people understand compound interest in the abstract. They know that money grows, and that growth accelerates over time. But abstract understanding doesn't change behavior. What changes behavior is seeing the numbers. A compound interest calculator turns a vague idea into a specific projection, and that specificity is surprisingly powerful. When you can see that saving an extra $200 a month in your thirties could mean an extra $300,000 by retirement, the decision stops being theoretical and starts being real. That's why these tools matter more than they get credit for. They don't just crunch numbers—they reframe how you think about money and time.
The math behind compound interest is straightforward, but the results are counterintuitive. A dollar invested today doesn't just earn a return—it earns a return on the return, and a return on that, and so on. Over short periods, the effect is modest. Over decades, it's transformative. The compound growth projections that calculators produce show this clearly, and they make the trade-off between spending today and saving for tomorrow much more concrete. That concreteness is the point. It's easy to ignore an abstraction. It's harder to ignore a number that represents your future.
The tools themselves are widely available and mostly free. Every major brokerage has one, and there are dozens of standalone calculators online. They all take the same basic inputs—starting amount, monthly contribution, expected return, and time horizon—and produce the same basic outputs—future value, total contributions, and total growth. The complexity isn't in the math. It's in choosing realistic inputs and interpreting the results correctly. That's where most people go wrong, and it's why understanding the calculator matters as much as using it.
What the Inputs Actually Mean
The starting amount is straightforward. It's what you have now. The monthly contribution is what you add each month, and it's the input that matters most for most people. A small change in monthly contributions produces a large change in the final result, because each contribution compounds for the entire time horizon. The investment return calculator that lets you adjust this input shows the power of consistent saving, and it's often the most motivating part of the exercise. Seeing that an extra $100 a month could add six figures to your retirement balance is a compelling argument for finding that $100.
The expected return is where most people make mistakes. It's tempting to use a high number, because a high number produces a bigger projection, and a bigger projection feels better. But unrealistic return assumptions produce projections that won't come true, and they can lead to under-saving. A more reasonable approach is to use a conservative estimate that reflects the historical returns of a diversified portfolio, adjusted for inflation if you want to see real purchasing power. The long-term wealth planning that works is built on realistic assumptions, not optimistic ones. The goal isn't to produce the biggest number. It's to produce a number you can trust.
The time horizon is the other input that matters enormously. The longer the horizon, the more powerful the compounding, because each year of growth builds on the last. A 40-year horizon produces dramatically different results than a 20-year horizon, even with the same contributions and the same return. That's why starting early matters so much, and why the calculators are most useful for younger investors. The compound growth projections that show a 40-year horizon make the case for starting now better than any argument could. The math is simply more compelling than the words.
It's worth being clear about what the calculator doesn't include. It doesn't include taxes, which can take a significant bite out of returns, especially in taxable accounts. It doesn't include fees, which can drag on returns over decades. It doesn't include inflation, unless you specifically adjust for it. A projection that ignores these factors is optimistic, and an optimistic projection can lead to under-saving. The financial growth strategies that work account for these factors, either by using a lower return assumption or by running the numbers with different scenarios. The goal is to understand the range of possible outcomes, not to pin down a single number.
Reading the Results Without Being Fooled
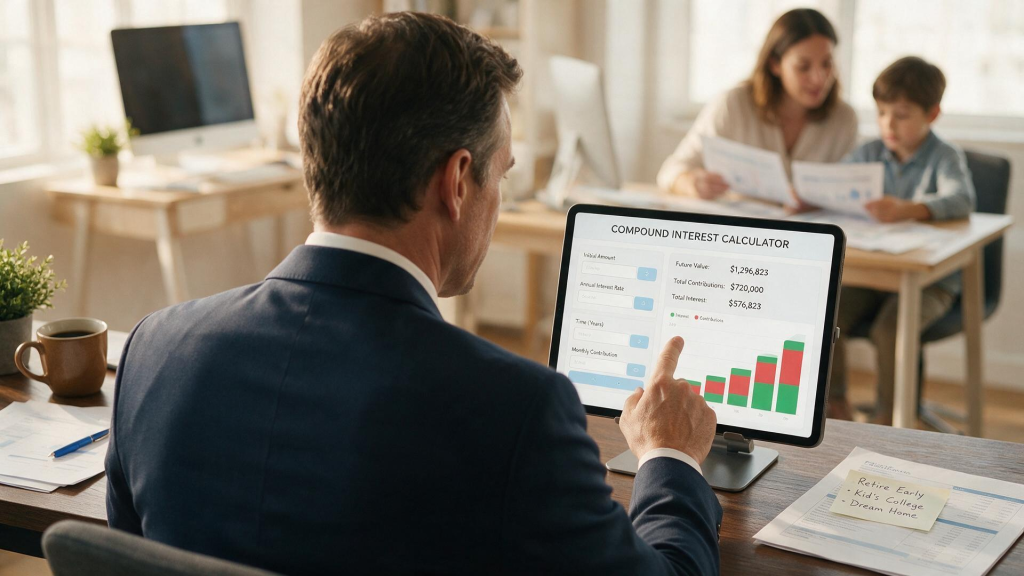
The most common mistake people make with calculators is treating the output as a prediction. It's not. It's a projection based on assumptions, and those assumptions may not hold. The market doesn't deliver a steady return every year. It delivers a volatile sequence of returns, some good and some bad, and the order matters. A projection that assumes a smooth 7% return every year will look different from a real portfolio that averages 7% but experiences significant ups and downs along the way. The investment return calculator is a tool for understanding the math, not for predicting the future.
Sequence-of-returns risk is a concept that calculators often ignore, and it matters especially for investors who are drawing on their portfolios. Two portfolios with the same average return can produce very different outcomes if the bad years come early versus late. A calculator that assumes a constant return misses this risk entirely, which can lead to overconfidence. The long-term wealth planning that's robust accounts for sequence risk, either by using a more conservative return assumption or by stress-testing the plan against a bad sequence of returns.
It's also worth running multiple scenarios. A calculator that produces one number can create a false sense of certainty. A more useful approach is to run the numbers with different return assumptions, different contribution levels, and different time horizons. That gives you a range of outcomes, which is more realistic than a single point estimate. The compound growth projections that show a range of scenarios are more useful for planning than ones that show a single number, because they help you understand the uncertainty involved and prepare for it.
The other thing to remember is that the calculator doesn't account for changes in your life. It assumes you contribute the same amount every month for the entire period, which is unlikely to be true. Your income will rise and fall. You'll have expenses that interrupt your saving. You'll have windfalls that boost it. A projection that assumes smooth sailing is a useful starting point, but it's not a plan. The financial growth strategies that work are flexible and adapt to changing circumstances, rather than rigidly following a projection that was made years ago.
Using the Calculator to Make Decisions
The most practical use of a compound interest calculator is to test the impact of different decisions. What if you save 5% of your income instead of 10%? What if you start five years earlier? What if you earn 6% instead of 8%? The calculator lets you see the consequences of those choices, and that visibility is what makes the decisions easier. Instead of guessing at the trade-offs, you can quantify them and make a more informed choice.
The calculator is also useful for setting goals. If you know you need $1 million for retirement, and you have 30 years and a reasonable return assumption, the calculator can tell you how much you need to save each month to get there. That's a concrete target, and concrete targets are easier to hit than vague aspirations. The long-term wealth planning that works is built on specific numbers, not general hopes. The calculator is a tool for turning those hopes into numbers.
It's also useful for understanding the value of time. The calculator shows that starting ten years earlier can be worth more than doubling your contributions later, because the earlier contributions have more time to compound. That insight is one of the most important in personal finance, and the calculator makes it visible in a way that words can't. The investment return calculator that shows the difference between starting at 25 and starting at 35 is a powerful argument for starting now, even if you can only contribute a small amount.
Finally, the calculator can help you stay motivated. Investing can feel abstract and slow, especially in the early years when the balances are small and the growth is modest. The calculator shows that the slow years are building toward something bigger, and that the growth accelerates over time. That's a useful perspective during the inevitable periods of doubt. The compound growth projections that show the curve bending upward are a reminder that the process works, even when it doesn't feel like it. And that reminder is often enough to keep you going through the lean years.
Pairing the Calculator With Real-World Action
The calculator is a tool, not a substitute for action. It can show you what's possible, but it can't make it happen. The most important step is to start contributing, even if the amount is small. The calculator shows that time is the most powerful variable in the equation, and time is the one thing you can't get back. Starting now, even with a modest amount, is better than waiting until you can afford a larger amount. The financial growth strategies that work are built on consistent action, not on perfect planning.
Automation is the most reliable way to stay consistent. Setting up automatic contributions from your bank account to your investment account removes the need to make a decision every month, and it ensures that you're contributing even when you're busy or distracted. The calculator assumes you contribute every month, and automation is how you make that assumption come true. It's a small step, but it's one of the most effective things you can do for your long-term wealth.
Reviewing the plan periodically is also important. Your income will change, your expenses will change, and your goals will change. A plan that made sense five years ago might not make sense today. Revisiting the calculator with updated numbers gives you a chance to adjust your contributions and keep your plan on track. The long-term wealth planning that works is a living process, not a one-time calculation.
The final piece is patience. Compound interest is a slow process in the early years and a fast one later on. The calculator shows that trajectory, but it can't make the early years feel faster. The investors who succeed are the ones who understand that the slow years are the foundation for the fast years, and who stay consistent through both. The investment return calculator is a reminder of why the patience is worth it. It shows that the math is on your side, as long as you give it time. And that's the most important lesson of all.