 By admin
What Blockchain Actually Is, Without the Hype
Blockchain has been called the most important invention since the internet, and it's also been dismissed as a solution in search of a problem. Both views miss the point. Strip away the buzzwords and the price charts, and what you're left with is a fairly simple idea with profound implications: a shared record of transactions that no single party controls, that can't easily be altered after the fact, and that anyone can verify. That's it. That's the core of blockchain technology explained in a way that doesn't require a computer science degree.
The way to understand it is by comparison. Think about how a bank keeps track of your money. The bank maintains a ledger — a record of who has what and who sent what to whom. You trust the bank to keep that ledger accurate, and you rely on the bank's authority to settle disputes. If the bank makes a mistake, or if someone inside the bank decides to alter the records, you're dependent on the bank's processes to catch it. Blockchain flips that model. Instead of one party holding the ledger, many participants hold copies, and they all agree on what the ledger says through a consensus mechanism. No single party can unilaterally change the record, because the other participants would reject the change.
That structure has real consequences. It means you can transfer value without a trusted intermediary, because the network itself provides the trust. It means records can be made tamper-evident, because altering one copy of the ledger would require altering every copy. And it means anyone with an internet connection can participate, because there's no gatekeeper deciding who gets access. Those properties don't solve every problem, and they're not always the right answer. But they're genuinely new capabilities, and they've spawned a wave of experimentation that's still unfolding. Understanding what blockchain can and can't do is the first step toward understanding where the blockchain innovation is likely to lead.
The Mechanics Behind the Technology
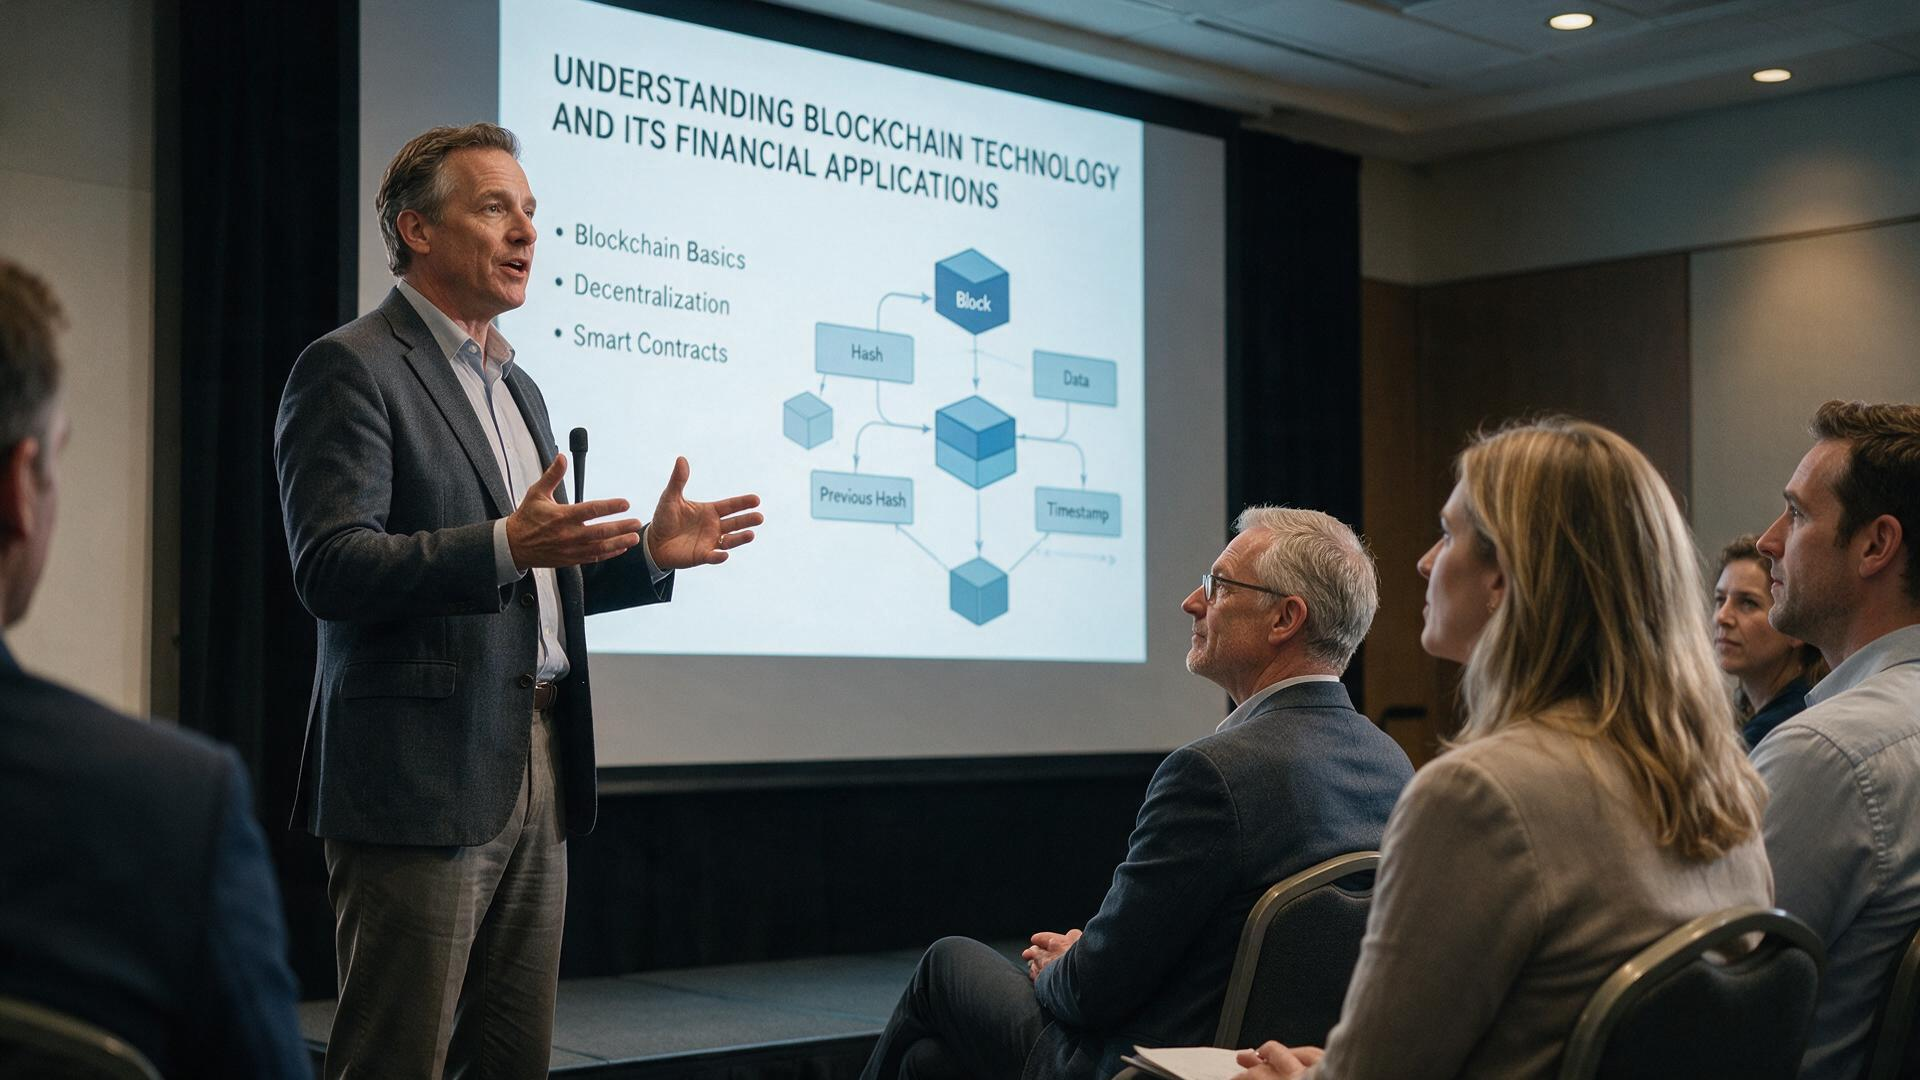
A blockchain is, at its core, a chain of blocks. Each block contains a batch of transactions, a timestamp, and a cryptographic reference to the previous block. That reference is what makes the chain a chain — each block is linked to the one before it, and changing an earlier block would break the chain and invalidate everything that follows. This is why blockchain records are described as immutable. They're not truly unchangeable, but changing them requires enormous effort and coordination, which makes tampering impractical for most purposes.
The other key piece is consensus. How do all the participants agree on what the ledger says, especially when some of them might be dishonest? Different blockchains answer that question differently. Bitcoin uses proof-of-work, where participants called miners compete to solve cryptographic puzzles and the winner gets to add the next block. The security comes from the enormous computing power required to attack the network. Ethereum uses proof-of-stake, where participants lock up their tokens as collateral and are selected to validate blocks in proportion to their stake. Both approaches have tradeoffs in terms of security, energy use, and decentralization, and the debate over which is better is far from settled.
Public versus private blockchains is another distinction worth understanding. Public blockchains like Bitcoin and Ethereum are open to anyone, and anyone can read the ledger and participate in consensus. Private or permissioned blockchains restrict access to a known set of participants, which makes them faster and more controllable but less decentralized. Many enterprise blockchain projects use permissioned networks because they need the auditability and shared-record benefits without the openness of a public chain. Both have their uses, and the choice depends on what you're trying to accomplish.
It's also worth understanding what blockchain doesn't do well. Public blockchains are slow and expensive compared to traditional databases, and that's a fundamental tradeoff rather than a temporary limitation. They achieve their security by having many participants duplicate work, which is inherently less efficient than having one party do it. For applications where speed and cost matter more than decentralization, a traditional database is often the better choice. The mistake is applying blockchain to everything when it's only the right tool for a specific set of problems.
The Financial Applications That Matter Most
Blockchain financial applications are where the technology has made the most progress, and for good reason. Finance is fundamentally about records, transfers, and trust, which is exactly what blockchain is good at. The most mature application is payments. Cross-border payments have traditionally been slow and expensive, because they involve multiple intermediaries, each of whom takes a cut and adds delays. Blockchain-based payment systems can settle transfers in minutes at a fraction of the cost, and that's a real improvement for businesses and individuals who send money across borders.
Stablecoins have become one of the most important financial applications, even if they don't get as much attention as other areas. A stablecoin is a blockchain token designed to maintain a stable value, usually pegged to the U.S. dollar. They've become a popular way to hold and transfer dollars outside the traditional banking system, especially in countries with unstable currencies or limited banking access. The volume of stablecoin transactions has grown enormously, and it's now one of the clearest examples of blockchain being used for something practical rather than speculative.
Tokenization is another area with significant potential. Tokenization is the process of representing real-world assets — stocks, bonds, real estate, art, commodities — as blockchain tokens. The benefit is that tokens can be traded more easily, divided into smaller pieces, and settled more quickly than traditional assets. A share of a building can be tokenized and sold to many investors, opening up real estate investing to people who couldn't afford a whole property. A bond can be tokenized and settled instantly rather than taking days. These applications are still early, but they're attracting serious interest from financial institutions.
Trade finance and supply chain finance are less glamorous but potentially transformative. International trade involves complex documentation and multiple parties, and blockchain can make the process more transparent and efficient. By creating a shared record of transactions, shipments, and documents, blockchain can reduce disputes, speed up settlement, and lower costs. Several major banks and shipping companies have experimented with these applications, and while adoption has been slower than some hoped, the potential is real.
Decentralized Finance and Its Promise
Decentralized finance, or DeFi, is the most ambitious application of blockchain to finance. The idea is to recreate financial services — lending, borrowing, trading, insurance, and more — without traditional intermediaries, using smart contracts that execute automatically when conditions are met. Instead of a bank approving your loan, a smart contract holds collateral and issues the loan according to rules written in code. Instead of an exchange matching buyers and sellers, an automated market maker does it algorithmically. The appeal is that these systems are open to anyone with an internet connection, operate transparently, and don't require permission from a gatekeeper.
The growth of DeFi has been remarkable. Billions of dollars are now locked in DeFi protocols, and the range of services available has expanded dramatically. Lending platforms let you earn interest on your assets or borrow against them, often without a credit check. Decentralized exchanges let you trade tokens directly from your wallet. Yield aggregators automatically move your funds to the highest-yielding opportunities. For people in countries with limited access to financial services, these tools can be genuinely empowering. For everyone else, they're an interesting alternative that sometimes offers better rates and sometimes offers worse ones.
But DeFi has serious problems that shouldn't be glossed over. Smart contract bugs have led to billions of dollars in losses, and many of those bugs weren't discovered until an attacker exploited them. Some protocols are governed by token holders who may not have the expertise to make good decisions, and governance attacks have been used to drain funds. Yields that look attractive are often funded by token emissions that are unsustainable, and when the emissions stop, the yields collapse. The regulatory landscape is also uncertain, and there's a real possibility that regulators will impose rules that change how DeFi operates.
Despite those problems, DeFi is worth paying attention to because it's showing what's possible. The idea of open, composable financial services — where protocols can be combined like building blocks — is genuinely innovative, and it's attracting serious developers and capital. The most likely outcome is a hybrid future, where some DeFi ideas get adopted by traditional finance while others remain niche. Understanding both the promise and the problems is essential if you're going to evaluate DeFi investments or participate in the ecosystem.
Where the Technology Is Headed
Digital financial technology is evolving quickly, and blockchain is becoming one part of a larger landscape rather than a standalone phenomenon. Central bank digital currencies, or CBDCs, are being explored by dozens of countries, and they borrow ideas from blockchain while being controlled by central banks. Tokenized deposits and stablecoins are being integrated into traditional payment systems. Major financial institutions are building blockchain-based infrastructure for settlement and custody. The technology is moving from the fringes toward the mainstream, even if it's not always obvious.
Scalability is one of the big areas of focus. Public blockchains have historically been slow, but layer-2 networks and other scaling solutions are making them faster and cheaper. These solutions process transactions off the main chain and then settle them on it, combining the security of the base layer with the speed of a centralized system. The technology is still evolving, but it's made real progress in recent years, and that progress is opening up new applications that weren't practical before.
Interoperability is another area to watch. Right now, different blockchains are largely isolated from one another, which limits their usefulness. Projects that enable assets and data to move between chains are being developed, and if they succeed, they could create a more connected ecosystem. That would make blockchain more useful for financial applications, because assets could flow freely rather than being trapped on a single network. It's still early, but the direction is promising.
Finally, regulation will shape the future of the technology as much as anything else. Clear rules can encourage adoption by giving institutions confidence, while unclear or hostile rules can push activity offshore. The regulatory landscape is still developing, and it varies significantly by country. Anyone following the space should pay attention to regulatory developments, because they'll determine what's possible and what isn't. The technology itself is impressive, but it operates in a world of laws and institutions, and those forces will shape how it develops. Understanding the technology is necessary, but it's not sufficient without understanding the context in which it's being deployed.